As you approach your senior years, there are some essential questions you need to ask yourself. Answering these will help you outline the framework for your life as a senior. It sounds simple, but naturally, there are many considerations and decisions you must make before finding the answers.
Society encourages you to continue working as long as possible, offering various benefits if you delay retirement. If you continue working beyond the state pension age, income subject to AM contributions from self-employment will not be deducted from your state pension. You can earn a senior premium, and you also have the option to defer your state pension if you wish.
If you transition to early retirement and are eligible for up to three years of this benefit, there is only one rate—the highest rate. You can still earn a tax-free premium if you continue working.
However, this is also the time to consider what brings you quality of life. Is it continuing to work, perhaps with reduced hours, or stopping entirely?
If you want to continue working
If you wish to continue working, different rules apply depending on your age. You can find more information in the fact sheets below, which are tailored to different retirement ages.
Each time you postpone your retirement by one year, you earn an additional annual salary and you also give your
pension savings the opportunity to grow.
Every year you postpone retirement, you earn an extra year's salary, and you also allow your pension savings to grow.
If you are not part of the early retirement scheme, partial pension might be an option, though this scheme is being phased out and will end by the close of 2025.
For more information about the state pension, you can read more here. If you want to know more about early retirement, you can read more here
Where?
Where do you want to live when you retire? Senior life is lived locally. Your dwelling is the physical setting of
your life, a part of your finances and your home, which may carry memories from a long and good life. Your dwelling
should meet your needs on the day you retire, as you will spend far more time at home.
Financial support
You may be eligible for benefits to help pay your housing expenses. Housing benefits are offered as a loan for
owner-occupied homes and co-operative housing units and as a subsidy for rental homes. You can calculate your
options at www.borger.dk.
Postpone taxation
When you or your spouse receives early retirement benefits, supplementary early retirement benefits, part-time
retirement benefits, state retirement pension benefits or anticipatory pension benefits, or reaches the age of 65,
you may have the option to freeze your property taxes.
For how long?
Life expectancy is increasing for both men and women
For quite some time, the trend has been that we live longer, and the indication is that this will continue. 20 years
ago, the average life expectancy for Danes was 72 years for men and 78 years for women, respectively. Today, the
average age for men is 77 years and for women 82 years.
While we should enjoy the prospect of living longer, we should also remember that a long life leads to greater
demands on our pension savings, as most people will need their savings to be paid out over a longer period of time.
Clearly, many different factors influence your life expectancy, such as genetics, your choice of career and your
lifestyle.
How much?
How much money will you need when you retire? Danica recommends that you have 80% of your previous income
when you retire, and that the majority of your savings are paid out as life-long benefits. But it is far from
certain that this fits your needs. If your lifestyle differs from most people’s, you should consider what is most
suitable for you – what it will cost you, or what you will save.
Think ahead
Maybe you also want to actively participate in society when you retire. Then you should consider ensuring that your
financial needs are not only inflation-proofed but that they are also adjusted for the cost of living. New
things happen all the time. New technology, new travel destinations, new housing standard demands, etc. And just
like when you were young, you do not want to live like your parents, but like everybody else.
Who is to inherit?
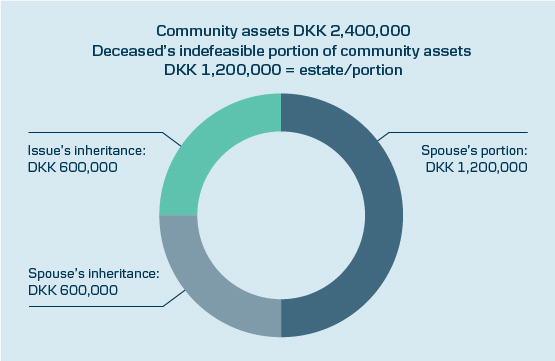
Who is to inherit your assets? If you are survived by a spouse and/or children or grandchildren, your assets will, as
a general rule, be distributed in equal shares between your spouse (50%) and your children or grandchildren (50%).
Distribution of your remaining assets according to the provisions of the Danish Inheritance Act
Do you prefer another distribution?
If you want your assets to be distributed differently, you need to consult an attorney and draw up a will. In many
cases, you can designate specific persons on your pension scheme outside the rules of the Danish Inheritance Act.
Keep in mind, however, that if you have a spouse and/or children or grandchildren, at least 25% of your estate must
be inherited by them. This means that you can leave 75% of your estate by will – and your entire estate if you leave
no beneficiaries entitled to an indefeasible portion of your estate.
We use data from our own and 3rd party cookies to remember your settings, traffic monitoring, improvement of our services and to send you relevant marketing information. For these purposes we profile you based on the collected data and on 3rd data collected from our partners. By navigating on our website you consent to our use of cookies. You may read more about our use of cookies here. If you reject cookies you must click here and we will not set cookies except required for site functionalities. You may always revoke your consent for our use of personal data for profiling and direct marketing as stated here.
Content is loading
Show
Hide
Show more rows: All table rows are already visible for screen readers.
Show less rows: All table rows are already visible for screen readers.